3 Ways Financial Advisors Are Paid – and What You Probably Aren’t Being Told

There are three primary compensation models for financial advisors; Commission-Based, Fee-Based, and Fee-Only.
1.Commission-Based Advisors
Generally, commission-based financial advisors earn their income through commissions on the financial products they sell – often products like:
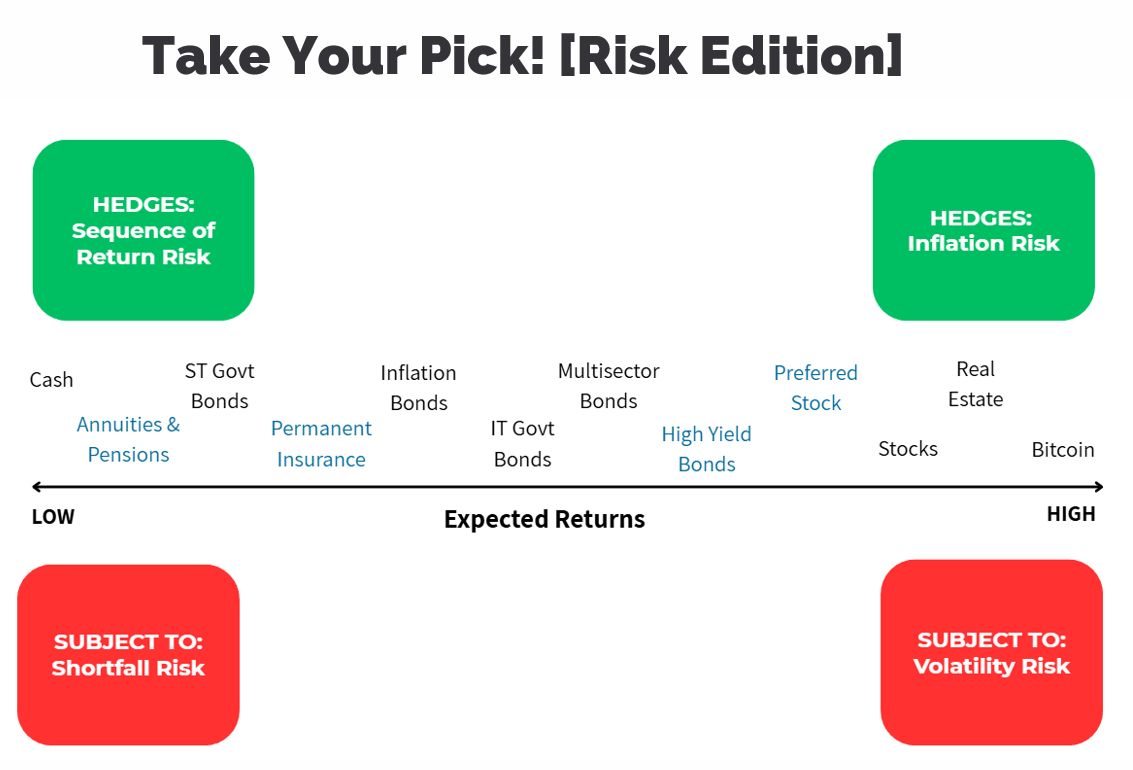
• Permanent Life Insurance such as whole life insurance, indexed universal life insurance (“IUL”), and variable universal life insurance
• Annuities such as variable annuities, fixed annuities, deferred annuities, and indexed annuities
While not an exhaustive list, firms like the below tend to employ commission-based agents that sell these types of products:
• Northwestern Mutual
• MassMutual
• New York Life
• Prudential
• Allianz
• Most companies you see on TV advertising insurance
The regulation of commission-based advisors is overwhelmingly complex, and involves several different regulatory bodies depending on what type of product is being sold, and on what type of account the sale pertains to (i.e. a 401(k) vs a taxable-brokerage account).
Absent the Department of Labor’s 2024 Retirement Security Rule holding up in the Courts (their attempts in 2010 and 2015 were unsuccessful), commission-based brokers are not subject to a Fiduciary Duty.
2.Fee-Based Advisors
Buckle up. This one is nuanced!
Fee-based advisors earn income through a combination of fees paid by clients and commissions from product sales. They can be thought of as a “hybrid advisor”, or sometimes referred to as a “dual-registrant” (more on that below). While exact statistics are difficult to calculate, the majority of financial advisors are fee-based advisors.
Under this hybrid model, fee-based advisors charge a fee for their advice-based services while also being able to earn commissions on the products they sell (annuities, permanent life insurance, mutual funds with commissions, etc.)
If you work with an advisor employed at firms such as the below, they are very likely a fee-based advisor:
• Edward Jones
• Thrivent
• LPL Financial
• UBS
• Charles Schwab
• Fidelity Investments
• Merrill Lynch
• Morgan Stanley
• Raymond James
• Ameriprise Financial
• The big banks’ wealth-management divisions such as JP Morgan, Bank of America, Citi, Goldman Sachs, Wells Fargo, etc.
• The bulk of SmartVestor Pros endorsed by Dave Ramsey / Ramsey Solutions
Fee-based advisors are “dual-registrants” because they are affiliated with 1) a Registered Investment Advisor (firms that give advice for compensation, and what subjects them to a Fiduciary Duty), AND 2) a broker-dealer (“brokering” transactions for securities or financial products in exchange for a commission and are NOT subject to a fiduciary duty).
In essence, fee-based advisors are subject to a Fiduciary Duty at certain times (under the Registered Investment Advisor arm), but not subject to a Fiduciary Duty when under the broker-dealer arm, which creates an ultra-confusing “hat switching” conundrum both for advisors and more importantly, the consumer!
3.Fee-Only Advisors
Fee-only advisors are compensated only through fees paid by their clients (hence, “fee-only”). They do not receive commissions or other forms of compensation from third parties. Fee-only advisors are the only compensation model where an advisor is legally bound to serve as a fiduciary-at-all-times. Because of this, it is often seen as the most transparent compensation model and aligned with the client’s best interests.
At True Riches Financial Planning, we are a Fee-Only advisor, meaning the ONLY way we are compensated is from the transparent, flat-fee we agree upon in exchange for Fiduciary-at-all-times, comprehensive advice around your entire net worth, cash flow, and taxes. We believe this is a necessary first-step towards ensuring our relationship is built on Trust, Radical Transparency, and seeks to mitigate as many Conflicts-of-Interest as possible.
If you are in search of fee-only, fiduciary advice for one all-in flat fee, Book a Discovery call today at a time that is convenient for you! No commissions, pushy product sales, or shenanigans here.
More from True Riches
Continue building your financial foundation


Christian Financial Planning to Invest, Give, and Live Abundantly.
Reach out for a complimentary "good fit" consultation.
